Dive Brief:
- Settlement of a cross-border payment at its destination remains a pain point across the industry, despite improvements in rails, speed and interoperability among players, payments executives said last week in a panel discussion.
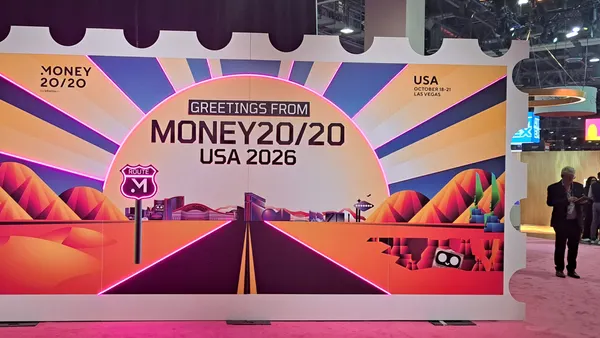
- The last portion of a cross-border payment accounts for 80% of the total speed of a transaction, regardless of the payment rail or instrument that is used, said Leigh Amaro, Americas CEO for Swift, the digital financial messaging firm for international payments. Amaro spoke about how cross-border payments are evolving on Oct. 20 at the Money20/20 financial technology conference in Las Vegas.
- Given current regulations, “an instrument can leave one country looking like one thing and completely end up in another's jurisdiction looking completely different,” Debopama Sen, Citigroup’s head of payments and services, said during the discussion. “And then when you marry that with regulatory cross-border restriction challenges, the last mile is where our clients struggle, and the last mile does need to be addressed.”
Dive Insight:
Cross-border payments totaled about $190 trillion last year, generating about $290 billion in revenue for the payments industry, according to an August report from the consulting firm McKinsey.
Three-quarters of Swift-enabled payments reach the recipient’s beneficiary bank within 10 minutes, Amaro said. At that point, however, local rules, operating hours and other challenges slow the settlement process, regardless of whether a payment was sent via stablecoin, tokenized deposit or a traditional rail, she said.
Meanwhile, regulators in many countries are pushing for more price transparency with respect to the services, while compliance complexity has increased due to newer fintech entrants into the cross-border arena, the McKinsey report noted.
Some of the costs and complexities of cross-border payments are slowly decreasing, threatening to commoditize the field, said Jonathan Zell, a McKinsey partner in the consulting firm’s payments practice, who moderated the session.
Kush Saxena, CEO of Banking Circle Group, a Luxembourg-based fintech that specializes in cross-border payments, challenged that contention, drawing a distinction between cash and data transfers.
“I wouldn’t say moving money is a commodity. I think moving data is becoming easier,” Saxena said, noting “a ton of interoperability” the industry has created above the fiat level. “When it comes to fiat, you get into sort of regulated territory, and … there is a 180-degree divide between where global commerce is going and between where regulators are going.”
One area that Citi and other banks are working to solve is “bridging the world of blockchain and digital assets with the fiat world” in cross-border payments, Sen said. She said Citi clients have been seeking this capability “because they’re not really looking at it, saying, ‘Hey, I want to use that technology.’ They’re saying, ‘Can you solve my problem?’”
Last month, Citibank introduced a cross-border, instant-payment service, using its global network and collaborating with Swift, to help customers avoid the need for local banking relationships.
“Data can move at the speed of light, but that’s not enough. The cash has to be available,” Sen said, noting the success of the M-Pesa money-transfer service in Africa due to its abundant cash-payout locations in each country.